Video Safety & Dash Cams
Telematics Insurance: How It Affects Fleet Premiums
Telematics insurance prices your fleet's real driving data on top of claims history. See what fleet safety data insurers review and how to bring it up.
How Does Telematics Insurance Work for Fleets?
With telematics insurance, insurers price your fleet's real driving behaviour, mileage and hours-of-service compliance, where they used to rely on blunt inputs. That is how telematics affects fleet insurance premiums. Commercial auto insurers have traditionally priced risk on vehicle type, driver history, claims history and a general industry risk category. Telematics data replaces the industry average with figures from the exact fleet they're underwriting. The change is part of a wider move toward usage-based and behaviour-based pricing in commercial insurance.
Personal auto insurance went this way first. Usage-based programs that track driving through a phone app or plug-in device have become mainstream there over the past decade. Commercial fleet insurance is following a similar path, with more at stake per policy and more data already on hand, since most commercial fleets running GPS tracking already generate the kind of data an insurer wants to see.
What Fleet Safety Data Do Insurers Use to Set Premiums?
When a commercial insurer does factor in telematics, the inputs look a lot like what your safety manager already tracks: harsh braking and acceleration, speeding against posted limits, idle time, verified mileage and hours-of-service compliance. You don't have to generate anything special for the insurer. Most GPS platforms already produce this data for internal safety and compliance work.
That overlap is the practical case for raising the subject with your insurer. If you already collect the data for your own safety program, a summary for the insurer costs nothing extra to produce. You export a report you already run, with no new data-collection process to build.
Fleet-wide safety trends count for more with an insurer than any single event. An underwriter cares less about one hard-braking incident six months ago than about whether your fleet's overall safety record is improving, holding flat or getting worse over a meaningful stretch of time. Telematics data is good at showing exactly that kind of long-run pattern.
Are There Telematics Discount Programs?
Some commercial auto insurers offer discount programs or premium credits for fleets that share telematics data, similar in concept to usage-based personal auto insurance. Availability varies a lot by insurer, region and program, and having a GPS platform installed doesn't automatically qualify a fleet. The only reliable way to find out is to ask your broker or insurer what data they would want and what it could be worth.
Ask too whether a program pays a flat discount for taking part or a variable one that adjusts with driving behaviour over time. The first rewards you for sharing data. The second rewards safer driving you can demonstrate, and knowing which one you're offered tells you how much of your safety-program spending will come back through insurance.
How Does Telematics Data Help in a Claims Dispute?
Telematics data, with or without video, also plays a growing part in claims. Verified speed, location and time data for the moment of an incident settles many disputes that would otherwise come down to conflicting driver accounts. That benefit is related to premium pricing but separate from it.
It holds even for fleets that never join a formal telematics discount program. With no premium benefit attached, clean and verified data you can hand an adjuster as soon as a claim is filed still tends to move the claim toward resolution faster than a driver's verbal account worked backwards.
How Do You Start the Conversation With Your Insurer?
Start with a direct conversation with your broker or insurer. Ask what telematics data, if any, they want access to, what format they expect, and whether sharing it carries a real premium benefit or mainly speeds up claims. Fleets that walk into a renewal with this data already organized tend to get further than fleets that assume a discount exists without checking.
Time the conversation around your renewal date instead of reaching out mid-policy. That is when an insurer is reassessing your risk profile anyway, so it pays the most attention and has the most room to adjust terms.
What Should You Put in Front of the Underwriter?
This is the package to export from the platform before renewal, and what each item tells an insurer. Send it sixty days ahead.
| Item | From | What it shows |
|---|---|---|
| Safety events per 100 km, by month, twelve months | Exception reports | The trend, which matters more than any single event |
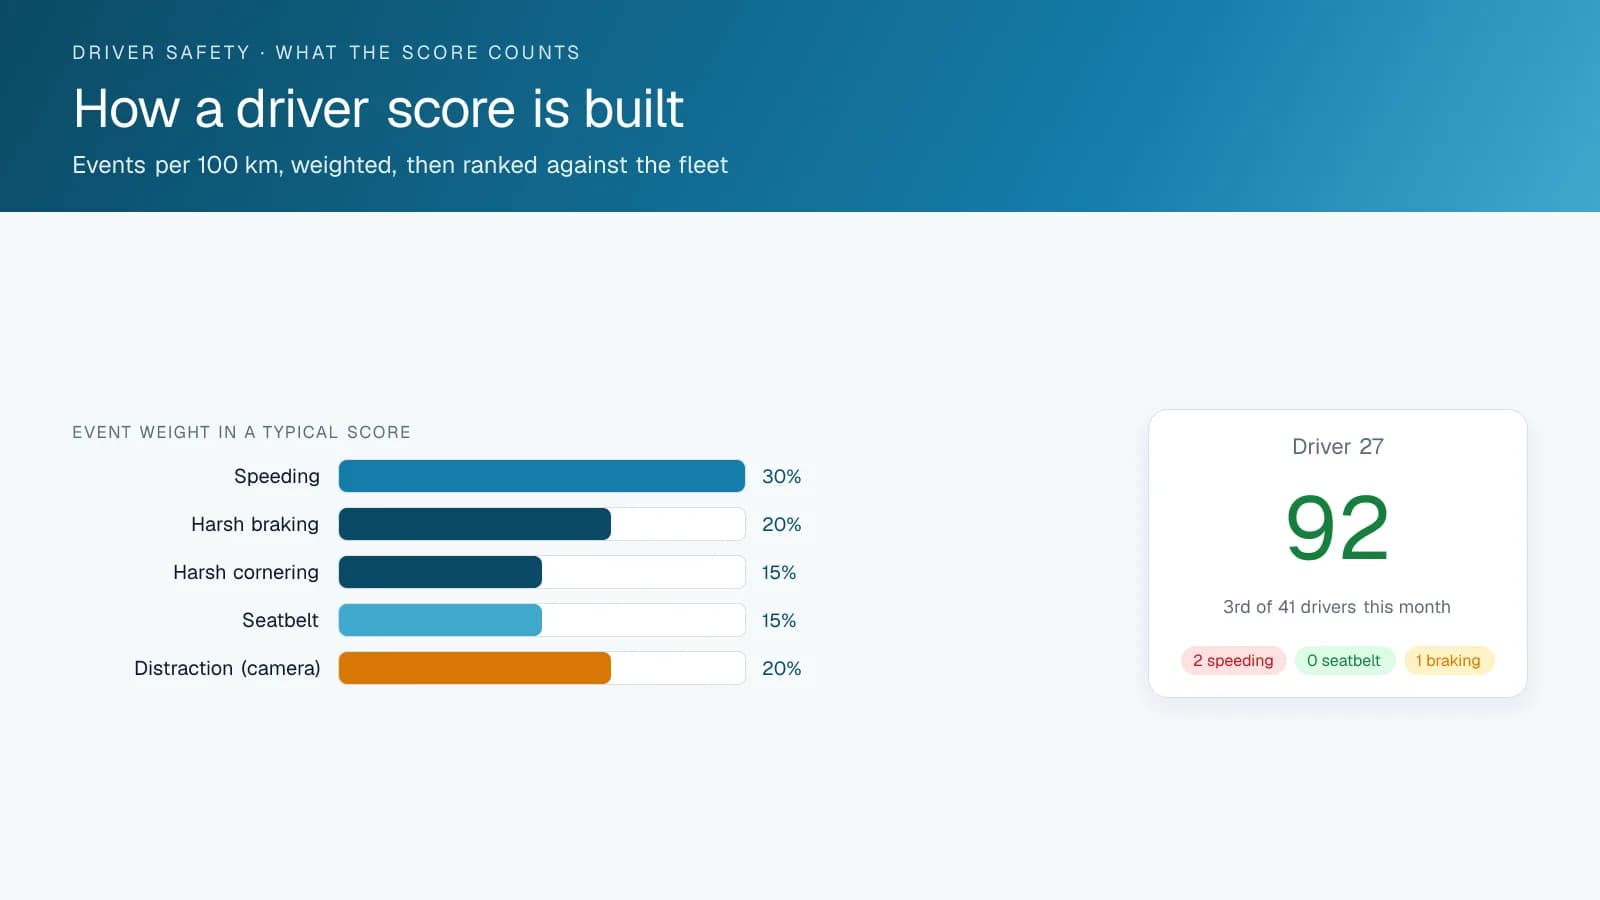
| Distribution of driver scores | Driver scorecard | Whether risk is concentrated in a few drivers, and what is being done |
| Speeding exceptions over posted limits | Speed rules | The most objective single risk measure |
| Hours-of-service violation rate | HOS report | Compliance discipline, and fatigue exposure |
| Verified distance by vehicle | Trip data | Exposure, measured rather than estimated |
| Claims defended or closed with video | Camera events and claim files | Loss history that is better than it would have been |
| The written safety program | Policy, training records, coaching log | That the data is acted on |
Frequently asked questions
Does GPS tracking automatically lower fleet insurance premiums?
No. Some insurers offer discount programs or premium credits tied to telematics data, but availability varies by provider, region and program, and installing GPS tracking doesn't qualify a fleet on its own. Ask your broker or insurer directly what data they want and what it could be worth before you assume a discount applies.
What telematics data do insurers typically want to see?
Insurers usually want the same data fleets already track internally: harsh braking and acceleration events, speeding against posted limits, idle time, verified mileage and hours-of-service compliance. It is rarely a special data set built for insurance, so you can export it as a report from the platform you already use.
Does this work the same way for Canadian and US fleets?
Not exactly. Programs and availability vary by insurer and region on both sides of the border, so the details differ from place to place. Either way, confirm with your own provider before assuming a program you heard about in the US applies in Canada, or the reverse.
When's the best time to bring up telematics data with an insurer?
Bring it up around your policy renewal date. That is when an insurer is actively reassessing your risk profile and has the most flexibility to adjust terms based on what you share. Have the data organized before the conversation so the underwriter can review the trend, not single events.
Sources
Related solutions & products
Related terms
Get a free quote
What are you looking for?